
8.5: Corporate Forecasting and Strategic Planning
- Page ID
- 88562
\( \newcommand{\vecs}[1]{\overset { \scriptstyle \rightharpoonup} {\mathbf{#1}} } \)
\( \newcommand{\vecd}[1]{\overset{-\!-\!\rightharpoonup}{\vphantom{a}\smash {#1}}} \)
\( \newcommand{\dsum}{\displaystyle\sum\limits} \)
\( \newcommand{\dint}{\displaystyle\int\limits} \)
\( \newcommand{\dlim}{\displaystyle\lim\limits} \)
\( \newcommand{\id}{\mathrm{id}}\) \( \newcommand{\Span}{\mathrm{span}}\)
( \newcommand{\kernel}{\mathrm{null}\,}\) \( \newcommand{\range}{\mathrm{range}\,}\)
\( \newcommand{\RealPart}{\mathrm{Re}}\) \( \newcommand{\ImaginaryPart}{\mathrm{Im}}\)
\( \newcommand{\Argument}{\mathrm{Arg}}\) \( \newcommand{\norm}[1]{\| #1 \|}\)
\( \newcommand{\inner}[2]{\langle #1, #2 \rangle}\)
\( \newcommand{\Span}{\mathrm{span}}\)
\( \newcommand{\id}{\mathrm{id}}\)
\( \newcommand{\Span}{\mathrm{span}}\)
\( \newcommand{\kernel}{\mathrm{null}\,}\)
\( \newcommand{\range}{\mathrm{range}\,}\)
\( \newcommand{\RealPart}{\mathrm{Re}}\)
\( \newcommand{\ImaginaryPart}{\mathrm{Im}}\)
\( \newcommand{\Argument}{\mathrm{Arg}}\)
\( \newcommand{\norm}[1]{\| #1 \|}\)
\( \newcommand{\inner}[2]{\langle #1, #2 \rangle}\)
\( \newcommand{\Span}{\mathrm{span}}\) \( \newcommand{\AA}{\unicode[.8,0]{x212B}}\)
\( \newcommand{\vectorA}[1]{\vec{#1}} % arrow\)
\( \newcommand{\vectorAt}[1]{\vec{\text{#1}}} % arrow\)
\( \newcommand{\vectorB}[1]{\overset { \scriptstyle \rightharpoonup} {\mathbf{#1}} } \)
\( \newcommand{\vectorC}[1]{\textbf{#1}} \)
\( \newcommand{\vectorD}[1]{\overrightarrow{#1}} \)
\( \newcommand{\vectorDt}[1]{\overrightarrow{\text{#1}}} \)
\( \newcommand{\vectE}[1]{\overset{-\!-\!\rightharpoonup}{\vphantom{a}\smash{\mathbf {#1}}}} \)
\( \newcommand{\vecs}[1]{\overset { \scriptstyle \rightharpoonup} {\mathbf{#1}} } \)
\(\newcommand{\longvect}{\overrightarrow}\)
\( \newcommand{\vecd}[1]{\overset{-\!-\!\rightharpoonup}{\vphantom{a}\smash {#1}}} \)
\(\newcommand{\ket}[1]{\left| #1 \right>}\)
\(\newcommand{\bra}[1]{\left< #1 \right|}\)
\(\newcommand{\braket}[2]{\left< #1 \vphantom{#2} \right| \left. #2 \vphantom{#1} \right>}\)
\(\newcommand{\braopket}[3]{\left< #1 \vphantom{#2}\vphantom{#3} \right| #2 \vphantom{#1}\vphantom{#3} \left| #3 \vphantom{#1}\vphantom{#2} \right>}\)
\(\newcommand{\qmvec}[1]{\mathbf{\vec{#1}}}\)
\(\newcommand{\op}[1]{\hat{\mathbf{#1}}}\)
\(\newcommand{\expect}[1]{\langle #1 \rangle}\)
\(\newcommand{\dfn}[1]{\emph{\textbf{#1}}}\)
A financial analyst will collect reliable financial data from internal numerous sources, if possible, which s/he will cite in his/her forecast, list the assumptions as part of the report, and “spread the numbers” accordingly. Interpretation and strategy then will follow.
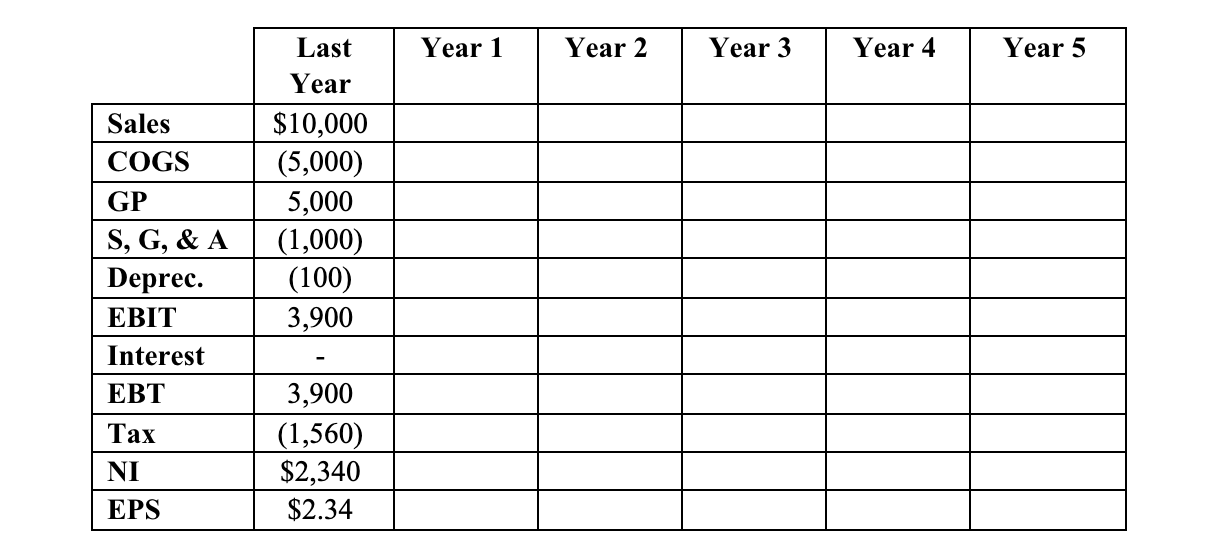
The following is an exercise in creating a pro forma (accounting-based) income statement. Later, we will see some analytic techniques, which may be implemented to convert “profits” to “cash flow,” if the latter is deemed more desirable. A “strategic plan” involves forecasting financial data for multiple future years.
Pro forma Financial Statements
Complete the pro forma I/S based on the following assumptions:
- Marketing projects sales growth at 10% p.a.
- “Purchasing” projects inventory costs to rise at a rate of 12% p.a. – due to scarcities.
- S, G, & A will grow at a rate of 8% p.a.
- For depreciation, see information below.
- Interest costs will rise due to acquisition of new property, $10,000 of which will be financed entirely via a 20-year, “non-amortizing” mortgage (i.e., interest-only) bond at a rate of 7.5%. The other $1,000 will be financed via retained earnings. The present property is fully paid for.
- Taxes are charged at a flat 40% rate.
- Calculate NI.
- Calculate EPS – There are 1,000s outstanding – no new shares will be issued.
Depreciation
- Next year’s (“Year 1″) depreciation expense will be $50. Thereafter the (old) building will be scrapped.
- At the end of Year 1, a new building will be in use (the cost of scrapping the old building will be included in the cost basis of the new building). At that time, a mortgage will be in place. The new building will cost $11,000 and will have a twenty-year life. It will be depreciated on a straight-line basis; a salvage value of $1,000 is assumed.